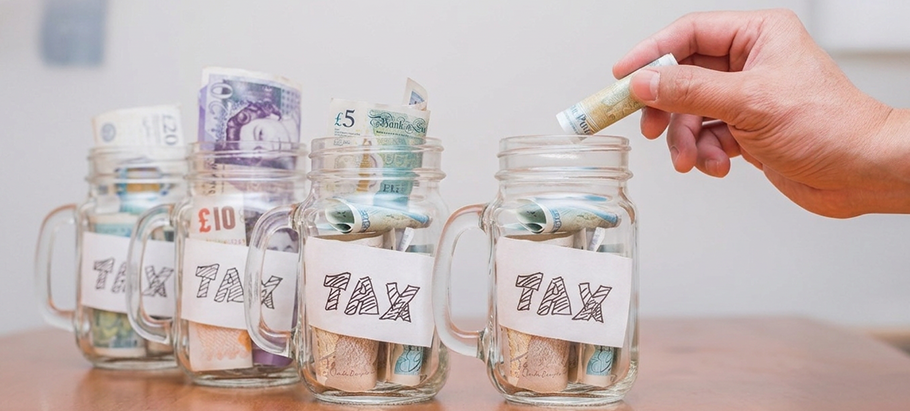
For self-employed clients, fluctuating income, business expenses, and household commitments can make it difficult to cover a large tax liability in one payment, even where substantial equity is held in a property.
A second charge mortgage could offer a suitable alternative to remortgaging or unsecured borrowing, depending on the client’s circumstances.
Preparing for the January Tax Deadline
A second charge mortgage allows eligible homeowners to raise additional funds against their property while retaining their existing first charge mortgage. This could be particularly relevant for clients with a competitive mortgage rate or an early repayment charge who want to avoid replacing their current deal.
Borrowing can be repaid over an agreed term, potentially helping manage cash flow. However, affordability, available equity, lender criteria, and completion timescales must all be considered. Depending on the lender, it may not be an instant solution, so options should be explored well ahead of the deadline.
The Cost of Missing the January Tax Deadline
Leaving a tax bill unpaid can add further pressure through interest and late-payment penalties.
HMRC’s published late-payment interest rate was 7.75% from 9 January 2026, although this rate is subject to change and should be checked against the latest HMRC guidance before publication or use.
Under current published self-assessment rules, late-payment penalties of 5% of the unpaid tax can apply at 30 days, six months, and 12 months after the payment deadline. Interest also accrues on the outstanding balance.
These additional costs can make an existing shortfall more expensive to resolve. Where suitable, a second charge mortgage could help a client raise the funds to settle a tax liability. However, the total cost of borrowing must be weighed against potential HMRC interest and penalties, alongside alternatives such as an HMRC Time to Pay arrangement, where interest may still accrue. The priority is to explore suitable options early, rather than allow the financial pressure to build.
Explore the Options with Positive Lending
Positive Lending works with brokers to explore specialist lending solutions for homeowners who need to capital raise or manage existing commitments, including where a straightforward remortgage or unsecured borrowing may not be the most suitable route.
For clients facing a sizeable tax bill, a second charge mortgage could be worth considering where retaining the existing mortgage is important and the additional borrowing is affordable and appropriate.
To discuss your next second charge case, call 01202 850 830 or email [email protected]